Define the vehicles and ordinary owner routine
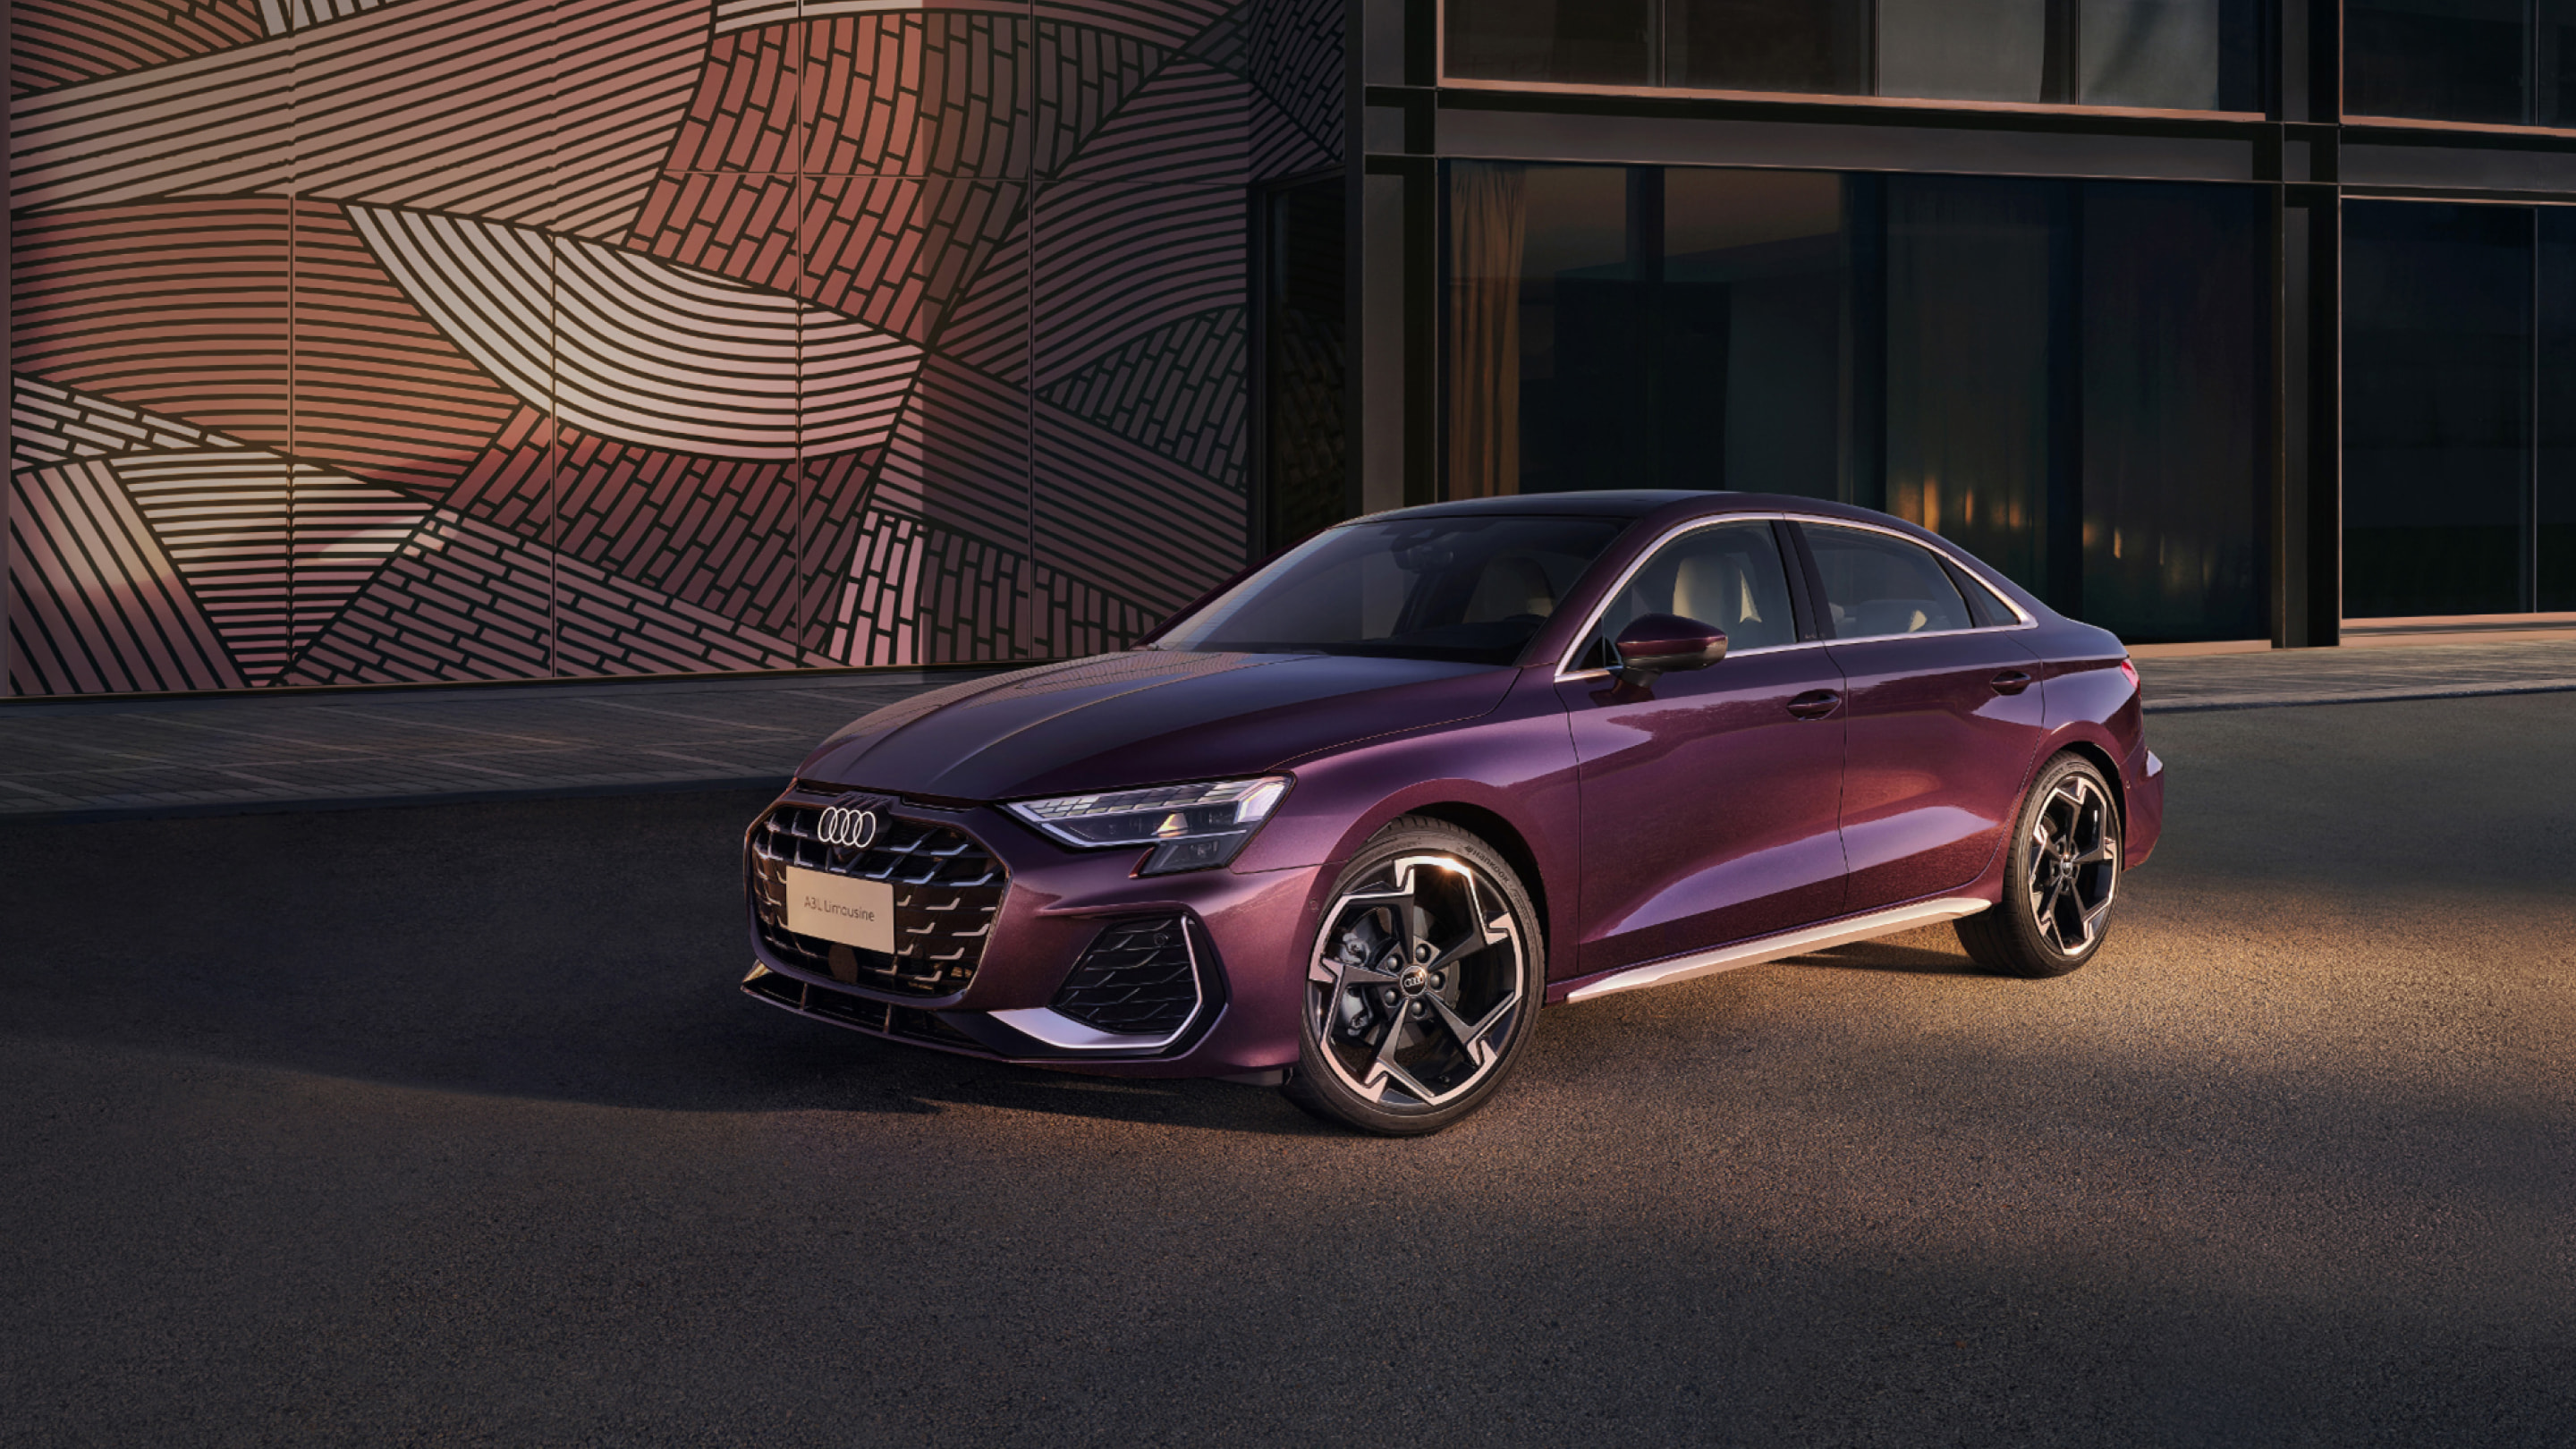
Identify original market, generation, body, fitted engine, gearbox and relevant propulsion through the specification guide. State the planned period, distance, ordinary trips, occupants and location. A similar advertised year does not make different systems equivalent. Record essential suitability before ranking options. The worksheet concerns specific acceptable candidates under one owner’s routine, not a universal annual amount for every A3. Keep sources beside inputs so a changed condition can be reviewed without reconstructing an unexplained total. Where an offer still depends on unconfirmed access, configuration or receiving acceptance, label that dependency before treating the calculation as a complete purchase comparison.
Begin with the full accepted acquisition boundary
Retain the dated actual vehicle proposal, examination, agreed work, transport and applicable receiving scope through the landed-cost guide. Keep currency, validity, responsible advice and exclusions attributable. Count included operations and objects once. A local prepared proposal and an export vehicle-only amount require different missing items before comparison. Consequential unknown diagnosis cannot become a confirmed amount because a contingency row exists. If essential acceptance remains open, show it as conditional. The arithmetic should not transform an unexamined lower asking price into a ready-to-use car simply because important condition or delivery inputs were omitted from the initial total.
Use paid energy under the actual pattern
Retain applicable dated fuel prices and labelled operating assumptions, distinguishing observations from reference context. For a plug-in proposal, use the no-private-charging decision to separate purchased electricity, fees and supported fuel-backed travel. Nominal capacity alone does not establish a paid bill. Do not transfer an updated global reference to an earlier configuration or compare unlike cycles as owner measurements. Show a credible less favourable energy case. Where the preference depends on future private charging or an unrealistically convenient routine, keep that dependency visible instead of quietly improving the use assumptions to make the preferred offer appear economical.
Quote applicable care and known work
Ask actual providers about relevant maintenance, consumables and assessed correction through the maintenance plan. Confirm market and body parts matching before using another configuration’s retail component amount. Parts prices are not completed operations. Generic care packages may exclude relevant fitted systems, diagnosis or completion evidence. Keep provider support and uncertain availability visible. Routine care, an understood present operation and unknown future repair are different input categories. A consequential current symptom should not disappear inside a small annual allowance, because greater numerical precision does not supply assessment or make an otherwise unsupported purchase acceptable.
Keep contingency, quotes and disposal distinct
Obtain applicable insurance and recurring quotations for the actual vehicle and location rather than importing another market’s charges. A contingency is a planning allowance, not a diagnosis or guaranteed repair limit. Future disposal proceeds remain uncertain; high trim, A3L body or a transmission choice cannot guarantee premium recovery. Cash expenditure and loss of value are different accounting views. If full acquisition is counted and disposal subtracted, do not add the same depreciation again. Show a conservative disposal case separately. The owner should understand whether the preference survives without an optimistic later sale that no current party has actually committed to provide.
Expose the input that changes the choice
Consider two accepted proposals where the lower acquisition amount belongs to a car requiring defined initial work. Count that operation once, then compare applicable care and paid-energy assumptions on the same routine. A conservative disposal case may change the preference; if so, identify that sensitivity instead of hiding it inside a precise total. If the choice remains coherent without optimistic recovery, preserve the practical reason. This example is not a forecast of invoices or resale. It demonstrates how known amounts, understood correction and future assumptions can be separated before a buyer relies on the apparently lower period cost.
Retain assumptions with the purchase record
Keep source dates, accepted preparation, support limits and relevant exclusions in the purchase schedule. A new VIN, destination or household pattern can reopen the worksheet. If consequential uncertainty dominates, obtain evidence or compare another supported offer rather than adding decimals to unknown inputs. The useful result is an explainable preference under explicit conditions, not a promise of every future expense. A cost worksheet cannot establish component lifespan, legal approval, fixed fuel use or disposal proceeds. It supports a decision about actual prepared value while keeping commercial amounts and technical acceptance connected but separate.